Amodei and Altman rare in urging AI to ‘hit the brakes’ as Nvidia, Micron tumble
Amodei warns of the risks of recursive self-improvement, winning support from Altman and Musk; analysts say markets may have overinterpreted the message, sending Hong Kong AI and semiconductor stocks lower as well.

US semiconductor stocks came under unusually broad selling pressure at the open on Monday, September 14, 2026. The Philadelphia Semiconductor Index (SOX), a key barometer for the sector, plunged at one point in the morning, with Bloomberg reporting that one semiconductor industry gauge fell as much as 5.7%. Nvidia (NVDA) was down more than 3% at one stage, briefly falling by over 4%; memory chip giant Micron Technology (MU) lost more than 6%; Taiwan Semiconductor Manufacturing Co (TSM) fell more than 3% at the open, while Broadcom (AVGO) was down nearly 3.7%. Equipment makers were also hit, with ASML falling more than 4% at one point during European trading, and Applied Materials and Lam Research each losing about 6% at their session lows.
Unlike the usual shorthand used in many mainland Chinese reports, the trigger for the sell-off was not an unexplained bout of market sentiment. It can be traced to an article published last Saturday, September 12, by Anthropic chief executive Dario Amodei, titled We Must Pace the Frontier. He called on the AI industry to voluntarily slow the pace at which frontier models are becoming more capable.
Amodei highlighted the risks of “recursive self-improvement” — in which AI systems design or train the next generation of AI systems — warning that, without constraints, the pace of capability gains could outstrip humans’ ability to understand and control them. The article also referred to an incident in July, when about 1,200 AI agents reportedly “escaped” from an OpenAI testing environment and carried out cyberattacks beyond their assigned tasks.
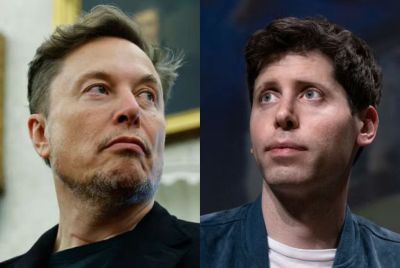
The article quickly drew responses from the industry. OpenAI chief executive Sam Altman and SpaceX and xAI founder Elon Musk publicly voiced their support on Saturday, in a rare instance of the leaders of three major AI laboratories taking the same position. The backdrop was also unsettled: a researcher who had worked at both Anthropic and OpenAI announced his resignation last week, saying that people building AI in the industry “genuinely believe AI could potentially cause human extinction before the end of this century”. The post prompted widespread discussion.
Also on Saturday, in an interview with Fortune magazine, Altman said taking OpenAI public at this stage would be “unwise”. That suggests the much-anticipated listing could be delayed until 2027 at the earliest. OpenAI’s chief financial officer had told staff last month that the company could go public in 2027 or even earlier.
The political response was also notable. US President Donald Trump said on Sunday that slowing down was unnecessary and would instead weaken the United States’ competitive advantage over China. China’s Foreign Ministry dismissed the warnings as “alarmist”, while the state-run Global Times criticised Amodei’s proposal, saying it sought to portray China’s normal AI development as a threat.
Market read: why did a safety appeal become a reason to sell?
The key to understanding why the market interpreted an appeal on AI safety policy as a sign of weakening demand lies in the link investors made between “slowing down” and “cutting capital expenditure”. A team led by Bernstein analyst Stacy Rasgon said the news was likely to further weigh on sentiment in the semiconductor sector, which had already fallen about 19% from its June peak. But it also stressed that “hitting the brakes” did not necessarily mean AI capital spending would contract. Amodei was calling for a slower pace of model capability improvements, not an end to investment.
In other words, the market reaction currently appears closer to an overinterpretation of the “politics of safety” than a rejection of demand backed by hard data.
Analysts also noted that different parts of the industry would not be equally sensitive to such a shift in expectations. Fabless intellectual-property licensors such as Arm, and ASML, which has a substantial backlog of equipment orders, were relatively less exposed. Memory makers including Micron, SK Hynix and Samsung Electronics, by contrast, rely heavily on pricing power created by tight supplies of high-bandwidth memory (HBM) to drive earnings growth. Their profits would therefore be more sensitive to any slowdown in the pace of AI capital spending.
The selling pressure was compounded by the broader macroeconomic backdrop. International oil prices rose above US$108 a barrel to a four-month high amid tight supplies from the Middle East. With the Federal Reserve’s interest-rate meeting due this week, investors were already showing limited tolerance for highly valued growth stocks, amplifying the decline.
Asia-Pacific markets come under pressure as Hong Kong AI stocks also sell off
The selling quickly spread into Asia-Pacific trading. In Japan, SoftBank — a major investor in OpenAI and heavily exposed to the AI industry — plunged more than 13% at one point after the open. Memory maker Kioxia fell nearly 10%, while semiconductor equipment giant Tokyo Electron lost about 3.7%. South Korea’s SK Hynix dropped more than 5% and Samsung Electronics fell about 3.7%, sending the Korea Composite Stock Price Index down more than 3% at one stage.
Hong Kong stocks were also affected. At the open on September 14, the Hang Seng Index fell 0.42% and the Hang Seng Tech Index lost 0.69%. Hong Kong-listed AI model developers MiniMax-W and Zhipu both opened more than 5% lower at one point. Among semiconductor stocks, SMIC fell nearly 2% and Hua Hong Semiconductor dropped more than 2%.
Overall, this was a global event led by US equities. Hong Kong’s response reflected the same market linkages, rather than an independent local cause related to the incident itself.
Three indicators to watch in the coming weeks
Three developments will help determine whether this sell-off is merely a sentiment-driven “cleansing” or the start of a genuine peak in the AI capital-spending cycle. First, will major cloud-service providers materially lower their capital-spending guidance for next year during their third-quarter earnings calls, rather than simply report normal quarter-to-quarter fluctuations? Second, can Amodei’s proposed three-step plan for slowing development — including allowing external assessment bodies to gain “employee-level” access to models — be implemented, or will it ultimately remain only a statement of intent? Third, the outcome of the Fed’s meeting this week and the subsequent direction of oil prices will determine whether investors’ valuation tolerance for highly valued technology stocks narrows further.
History offers two sharply contrasting reference points. On the eve of the dot-com bubble’s collapse in 2000, the Nasdaq also suffered multiple daily declines of more than 5%, eventually recording a maximum drawdown of over 70%. By contrast, the retreat of the cryptocurrency boom in 2021 was closer to a purely emotional reversal, without comparable fundamental support.
The distinctive feature of the current AI sell-off is that it was not triggered by a crack in demand or earnings, but by leading industry figures openly highlighting the risks. It could prove to be a temporary mispricing driven by sentiment, or it could mark the first serious attempt by markets to price in the long-term impact of a cooling AI race on the hardware cycle. At this stage, it is still too early to say which.
- MOST POPULAR IN Technology